

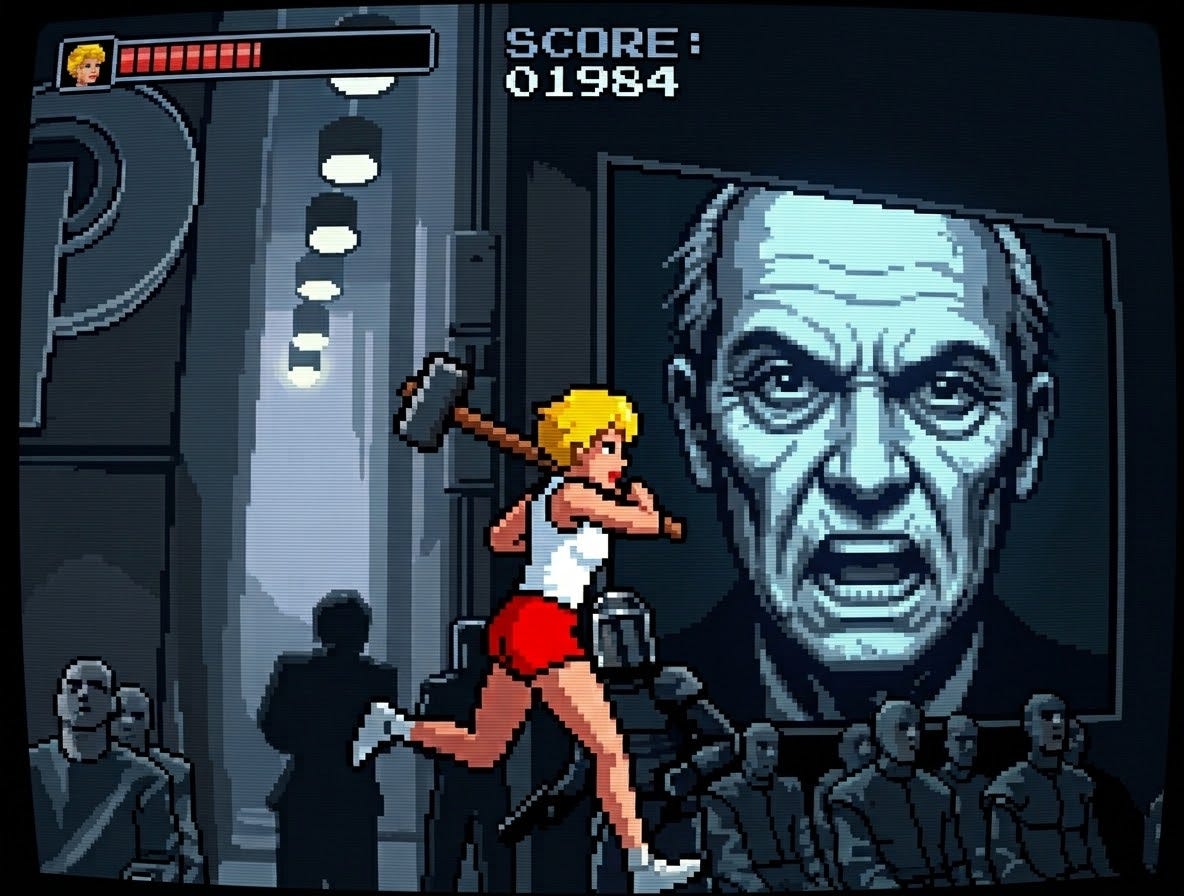
As I was sitting in the audience this past Thursday at Fintech NerdCon listening to Cetin Duransoy explain how Revolut is going to take over retail banking in the US with only 180 domestic employees, I experienced a flurry of emotions. My first thought was, holy shit, this is bad for credit unions. But the more I listened, the more it sounded like a reboot of Ridley Scott’s famous “1984” Apple commercial. Except in the reboot, technology wasn’t throwing the hammer; technology (presumably an AI agent) was the one who instituted the Information Purification Directives.
Next on stage was Immad Akhund repeating basically the same message, but with Mercury subbed in for Revolut and SMB banking subbed in for retail banking. About that time, two things dawned on me:
In all this talk, I never once heard the word community.
In my reboot, I had not yet cast the hammer thrower.
Suddenly, the lens came into focus. If AI-overloaded technology was the oppressive establishment in my upside-down world, the hammer had to be community. And – you guessed it – credit unions had to be the girl in the red shorts.
What Is Community, Anyway?
Later that day, I ran into two colleagues separately and noted to each one that nobody seemed to want to talk about community. Much to my surprise given that both these gentlemen work in community banking, both said that community in the traditional sense has lost its relevance, further explaining that technology has redefined community. As an example, one observed that Chime customers are called members, as if that designation somehow bound all Chime customers together as a community.
Sorry, friends, but I’m calling bullshit.
I think working in fintech creates an echo chamber where everyone wants to run their finances through ChatGPT as a safety net and is salivating at the thought of having an AI agent on tap that can hunt down a better CD rate every five years. But that’s not what I see out in the real world.
People upport their championship high school football team. They run for local office. They buy dinner at the mom-and-pop pizza parlor. I could go on and on and on. The bottom line is: People that I know really do care about their IRL community. What’s more, in the “us vs them” of big bank/corporate dominance that is often at odds with the community, credit unions can easily position themselves on the “us” side. Credit unions exist to serve real communities, not fake “we’re gonna slap a member label on your ass and call it done” communities.
The Gift They Don’t Even Know They Gave
After I had a chance to digest the messaging of Convolut … I mean Revolut, Mercury and others, I wasn’t scared at all. In fact, I was grateful – grateful that these titans of fintech laid out the perfect playbook for credit unions and other community financial institutions.
As a credit union, you must understand and accept that you’ll never win the technology game. However, it’s never been cheaper and easier to be competitive in that game. All you have to do is keep that score close. Just stay equally focused on the community game and you’ll be like Kobe Bryant putting up 81 points on the Raptors. (When I think competitive, I automatically think of the Mamba.)
If the neobanks and megabanks think they’re gonna bury credit unions in their own confusion, they have another thing – and a really big hammer – coming.
We shall prevail!